IRS Worker Classification Rules for 2026: Employee or Independent Contractor?
Correctly classifying workers is one of the most important payroll decisions a business can make. A worker’s classification determines whether payroll taxes must be withheld, which tax forms must be filed, and whether the business could face IRS penalties for worker misclassification.
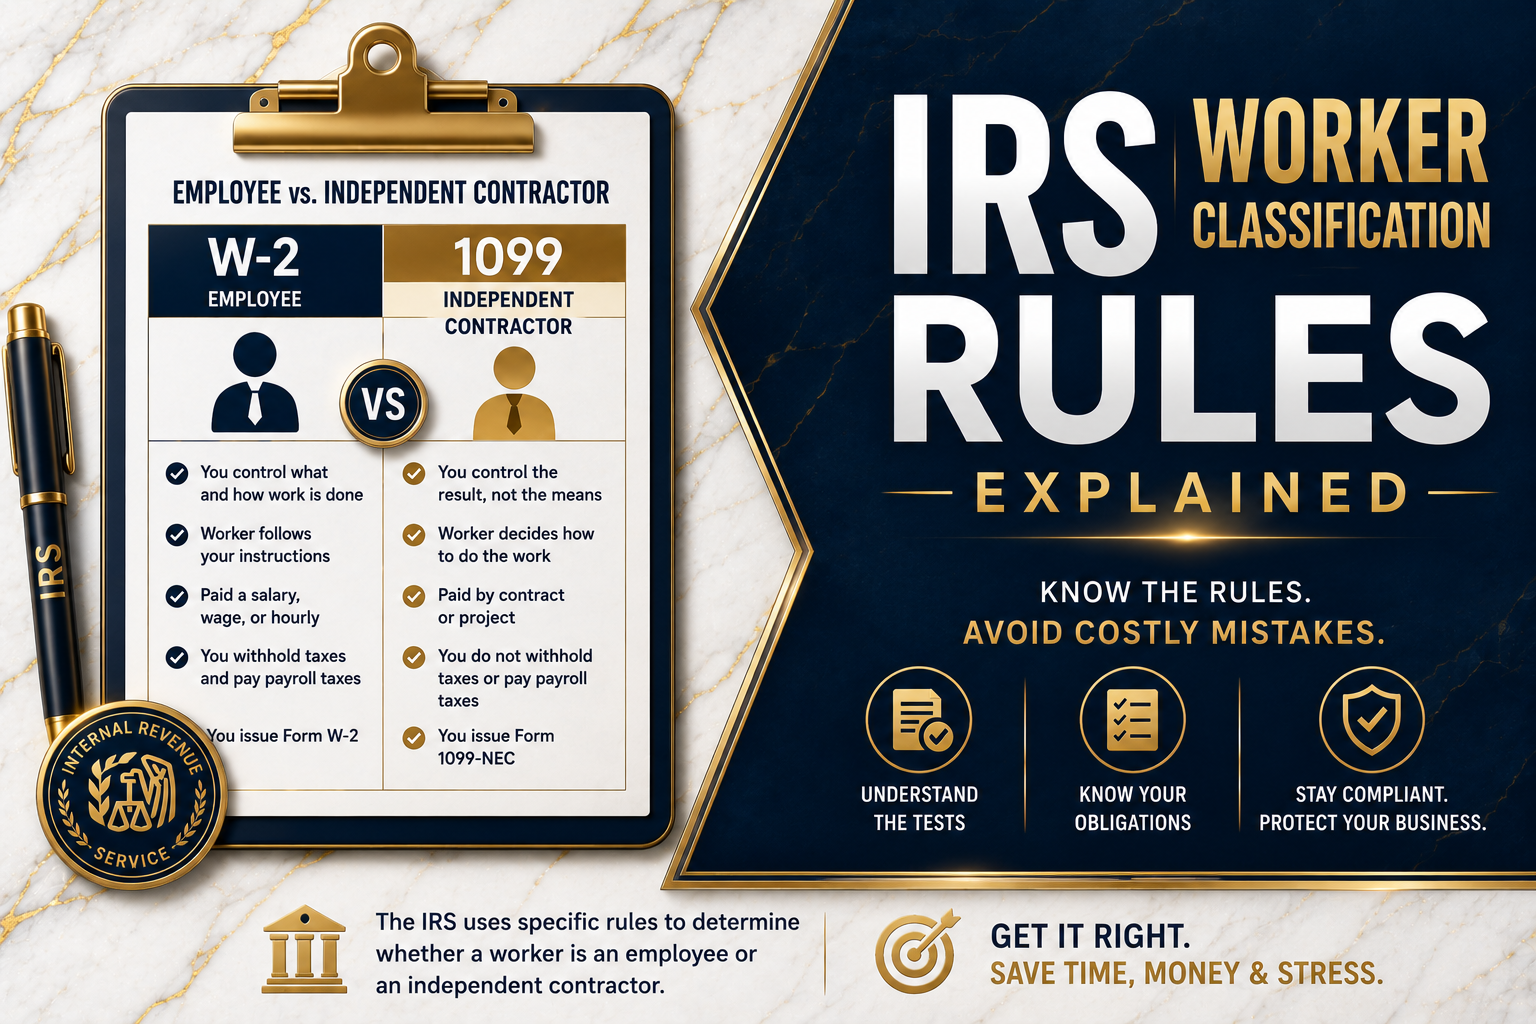
For 2026, the IRS continues to apply the common-law control test. The deciding factor is not what a contract says—it’s whether the business has the right to control how the work is performed.
The IRS Common-Law Control Test
In general:
- Employee: The business has the right to control both what work is performed and how it is performed.
- Independent Contractor: The business controls only the final result—not the methods or means used to complete the work.
Even if a business does not actively supervise a worker every day, simply having the right to direct how the work is performed may establish an employer-employee relationship.
The Three IRS Classification Factors
The IRS evaluates every worker relationship using three primary categories.
1. Behavioral Control
A worker is more likely to be an employee when the business directs how the work must be completed.
Examples include:
- Setting work schedules
- Providing detailed instructions
- Requiring specific procedures
- Providing tools or equipment
- Selecting assistants or support staff
- Training workers to follow company methods
Generally, extensive instruction and training indicate employee status.
2. Financial Control
The IRS also considers who controls the financial aspects of the work.
Independent contractors often:
- Pay their own business expenses
- Purchase and maintain their own equipment
- Provide services to multiple clients
- Invoice by project or contract
- Have the opportunity to realize a profit—or incur a loss
Employees generally have less financial risk because the employer typically provides the resources necessary to perform the job.
3. Relationship Between the Parties
The IRS examines the overall relationship, including:
- Written contracts
- Employee benefits
- Whether the relationship is ongoing or temporary
- Whether the worker performs services that are a key part of the business
Although written agreements are important, they do not override the actual facts and circumstances of the working relationship.
Payroll Tax Responsibilities
If the Worker Is an Employee
The employer generally must:
- Withhold federal income tax
- Withhold Social Security and Medicare taxes
- Pay the employer share of Social Security and Medicare taxes
- Pay federal unemployment (FUTA) tax
- Issue Form W-2
If the Worker Is an Independent Contractor
Generally, the business:
- Does not withhold payroll taxes
- Does not pay the employer share of Social Security and Medicare taxes
- Reports qualifying payments on Form 1099-NEC when required
Special Worker Categories
Statutory Employees
Some workers are treated as employees for Social Security and Medicare tax purposes even if they would not otherwise qualify under the common-law rules.
Examples include certain:
- Agent or commission drivers
- Life insurance salespersons
- Homeworkers
- Traveling or city salespersons
Statutory Nonemployees
Certain workers are treated as self-employed by law if IRS requirements are met, including:
- Licensed real estate agents
- Direct sellers
- Certain companion sitters
Misclassification Can Be Costly
If the IRS determines that a worker should have been classified as an employee, the business may become responsible for:
- Back payroll taxes
- Interest
- IRS penalties
- Additional employment tax assessments
In certain situations, relief may be available if the employer had a reasonable basis for treating the worker as an independent contractor, consistently filed the required information returns, and satisfied other IRS requirements.
Need an Official IRS Determination?
If worker classification is uncertain, either the business or the worker may request an official IRS determination by filing Form SS-8.
The IRS reviews information provided by both parties before issuing its determination regarding federal tax classification.
Key Takeaways
✔ Worker classification depends on the facts—not contract language alone.
✔ The IRS evaluates behavioral control, financial control, and the overall relationship.
✔ Employees generally require payroll tax withholding and Form W-2 reporting.
✔ Independent contractors generally receive Form 1099-NEC and are responsible for their own self-employment taxes.
✔ Special IRS rules apply to statutory employees and statutory nonemployees.
✔ Reviewing worker classification before hiring can help prevent costly IRS payroll tax issues.
Need Help Classifying Your Workers?
Our CPA team can help you evaluate worker relationships, comply with IRS payroll tax rules, and reduce the risk of costly worker misclassification penalties before they become a problem.
Contact our CPA team today for guidance on worker classification, payroll tax compliance, and proactive employment tax planning.
Proper worker classification today can help your business avoid costly payroll tax issues tomorrow.